
Opinion
The Complexities Hidden in the 'One Big and Beautiful Bill': How Corporate Tax Teams Can Get Ahead
The 'One Big and Beautiful Bill' (OBBBA) brings significant opportunities for corporations, including 100% bonus depreciation, immediate deduction of domestic R&D expenses, and permanent transferability of tax credits, but it also introduces new challenges such as state-level tax law compliance and interactions between provisions. Tax teams need to manually review state consistency, pay attention to the impact of the GILTI renaming, and seize the window for accelerated depreciation elections in 2025-2026.
The Quietly Eroding EBITDA in the Middle Market: The Hidden Cost of Cumulative Capitalization Drift
In middle-market private companies, a phenomenon known as 'cumulative capitalization drift' is quietly suppressing EBITDA. This article analyzes its causes, manifestations, and impacts, and proposes strategies such as interim reviews to help CFOs unlock undervalued enterprise value.
The Only Contract That Matters: How Cash Flow Forecasting Dominates Private Credit Stress Tests
When the $1.7 trillion private credit market undergoes its first real stress test, market focus centers on fund-level liquidity and investor redemptions, but the health of underlying borrowers is what truly matters. Andres Pinter, Senior Managing Director at Ankura Consulting, speaking from a corporate restructuring expert's perspective, notes that the most critical indicator of a company's debt-servicing capacity is cash flow, not GAAP profits or adjusted pro forma figures. The 13-week cash flow forecast, as the most honest financial tool in American capitalism, is evolving from a restructuring-specific instrument into a required course for investors across all asset classes.
The Mathematical Foundation of AI Business Cases Is Wrong: A Shift from Cost Accounting to Throughput Accounting
An NBER study shows that over 80% of companies report no significant impact of AI on employment or productivity, yet executives still predict AI will boost productivity by 1.4% over the next three years. This article argues that this stems from the evaluation trap of cost accounting, and uses Goldratt's Throughput Accounting as an alternative framework, emphasizing that AI should act on system bottlenecks rather than local efficiency. It cites cases from Forrester, PwC, Klarna, and Air Canada, pointing out that mis-evaluation leads to value destruction.
The Key Role of CFOs in Turning Around Loss-Making Enterprises
When an enterprise incurs losses, CFOs are often blamed, but they actually bear the fundamental responsibility of guiding the enterprise toward profitability. This article, written by Diya Sagar, CFO of AWA Studios, shares her experience in turning around losses: first, it is necessary to distinguish between temporary losses and fundamental failures, then focus on controllable levers, such as optimizing unit economics, rather than blindly cutting costs. The article emphasizes that when approaching profitability, risk tolerance should be increased, investment should be made in growth opportunities, and it should be recognized that turnaround takes time, ultimately validating the CFO's capability through financial performance.
The 'Athlete Tax' from a CFO's Perspective: Compliance Challenges of Cross-State Payroll Taxation in Light of Sam Darnold's Case
Sam Darnold won the Super Bowl but received a $249,000 tax bill from California, sparking widespread discussion. This article clarifies the facts, explains how the 'athlete tax' works, its historical background, and differences in state tax rates, illustrates its impact through three cases, and finally offers compliance recommendations for CFOs.
Liquidity is returning. Are companies ready?
The period of capital constraints may be ending, with private equity pipelines building, strategic buyers reopening dialogues, and refinancing discussions taking shape anew. But liquidity does not automatically create value; it only amplifies the existing foundation. CFOs should answer in advance: if new capital arrives tomorrow, where will it be deployed? Can leadership align on key initiatives within 24 to 36 months, supported by credible modeling for decision-making?
The Cash Flow Lever Most CFOs Overlook in a Tariff Environment
Facing tariff measures targeting Canada, Mexico, and China since 2025, export companies are responding to pressure by reshoring production and switching to domestic suppliers. However, these operational decisions may unexpectedly unlock eligibility for IC-DISC tax benefits. This article explains how IC-DISC converts export income from ordinary tax rates to preferential dividend tax rates, yielding permanent federal tax savings of 5.8 to 13.2 percentage points, and analyzes compliance and strategic considerations following the Supreme Court's ruling in February 2026.
Operations of Self-Funded Health Plans: The Actual Boundaries of the Finance Department's Responsibilities
Self-funded health plans are becoming an important option for companies to control healthcare costs, but their essence is shifting from purchasing insurance to operating a health plan. The finance department must confront new responsibilities such as cash flow volatility, reserve strategies, employee cost sharing, HIPAA compliance, and multi-vendor reconciliation. Based on industry observations from Michael Paull, President and CFO of Ahola Corporation, this article outlines the core work and potential benefits of finance under the self-funded model.
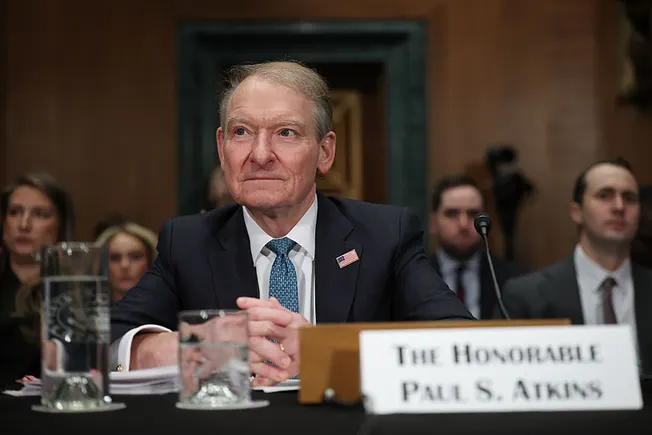
Is SEC Regulation Still Stuck in the Pre-AI Era?
Sandy Peters, Head of Financial Reporting Policy at CFA Institute, writes that SEC Chairman Paul Atkins has revived the "disclosure overload" narrative, but in an era where AI is reshaping information production and consumption, this narrative lacks a technological perspective and empirical support. The article questions the SEC's logic of measuring disclosure burden by page count and advocating for reduced disclosures to increase the number of listed companies, and lists a series of questions the SEC must answer before issuing a concept release.