
Is SEC Regulation Still Stuck in the Pre-AI Era?
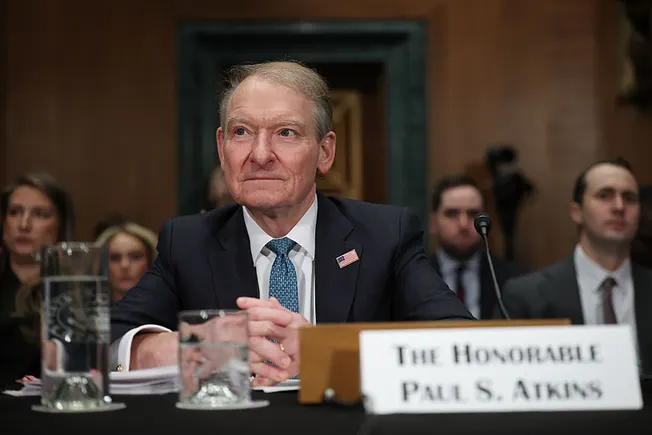
Sandy Peters, Head of Financial Reporting Policy at CFA Institute, writes that SEC Chairman Paul Atkins has revived the "disclosure overload" narrative, but in an era where AI is reshaping information production and consumption, this narrative lacks a technological perspective and empirical support. The article questions the SEC's logic of measuring disclosure burden by page count and advocating for reduced disclosures to increase the number of listed companies, and lists a series of questions the SEC must answer before issuing a concept release.
This article is a guest post by Sandy Peters, Head of Financial Reporting Policy at CFA Institute, and reflects the views of the author alone.
In December 2025, the AICPA Conference on Current SEC and PCAOB Developments opened with a conversation with U.S. Securities and Exchange Commission (SEC) Chair Paul Atkins. Atkins did not address the long-debatedquarterly versus semi-annual reportingissue, but instead focused on disclosure, expressing particular concern about so-called "disclosure overload."
This narrative is not new. In 2013, CFA Institute questioned the premise of "disclosure overload" in a report titled "Financial Reporting Disclosures: Investor Perspectives on Transparency, Trust, and Volume."reportAt that time, a growing number of commentators claimed that investors were overwhelmed by the volume of corporate disclosures, but notably, these discussions rarely included serious consideration of technology.
The 2013 report noted that investors were in the midst of technological change and were not actually complaining about excessive disclosure volume. CFA Institute cited Jamie Dimon's comments at the 2013 World Economic Forum about the page count of JPMorgan Chase's 2012 Form 10-K as one example, and pointed out that investors do not print such documents but rather read them electronically through data service providers and technology.
At the time, then-SEC Chair Mary Jo White also echoed the "disclosure overload" narrative. However, within months after the CFA Institute report was published, the focus of regulatory discussions shifted from "disclosure overload" to "disclosure simplification" and "disclosure effectiveness."
Fast forward to 2025. Recent remarks by Chair Atkins and other SEC commissioners have revived the "disclosure overload" narrative—this time against the backdrop of rapid advances in artificial intelligence. Unlike in 2013, failing to consider technology in the analysis is no longer merely puzzling but highly anachronistic.
Recent media reports and conference agendas show that AI is increasingly being used to prepare financial information. At the same time, investors are increasingly relying on AI and large language models to analyze disclosures and support investment decisions. When both the production and consumption sides of information are undergoing fundamental change, the SEC's "disclosure overload" narrative is increasingly difficult to reconcile with current technological realities.
The case of risk factors: why this argument falls short
At the AICPA conference, Chair Atkins cited the length of the "Risk Factors" section in Form 10-K as evidence of "disclosure overload," again pointing to page counts. But from an investor perspective, this example is unconvincing.
First, page counts are largely irrelevant. Investors, especially younger generations, access information through data service providers, structured datasets, and electronic filings. They do not experience disclosures as stacks of 8.5x11-inch paper.
Second, investors are increasingly using AI tools to analyze risk factor disclosures quickly and at scale. These tools enable investors to capture subtle changes over time and ask critical questions: Why was this risk factor modified? What new risk is management signaling? In this context, volume is not noise; change is information.
Over the past year, the SEC has increasingly suggested that reducing disclosures would help increase the number of public companies. However, the Commission has provided no empirical evidence to support this claim, nor has it demonstrated that disclosure requirements are a significant driver of the long-term decline in the number of public companies.
Correlation is not causation. To date, the SEC has neither proven that stricter disclosure requirements have caused companies to choose not to go public, nor that previous disclosure simplification efforts have materially increased the number of public companies.
Questions the SEC must answer
Before issuing any concept release aimed at reducing disclosures, the SEC has an obligation to provide market participants with clear, evidence-based answers to several fundamental questions.
Regarding disclosures
- How did the SEC conclude that Regulation S-K generates a significant amount of immaterial information?
- Has the SEC conducted meaningful investor surveys to support this conclusion, or is this narrative primarily driven by issuer concerns?
- What impact have the SEC's disclosure simplification initiatives over the past decade had on the number of public companies?
- Given that much of Regulation S-K is principles-based, how could it systematically lead to the disclosure of immaterial information?
- How does the SEC assess whether the cost savings from reducing disclosures might be outweighed by the potential costs of higher equity risk premiums and capital costs? Does the SEC believe that reduced transparency would lower the cost of capital?
Regarding the number of public companies
- Has the SEC analyzed whether increased regulatory and disclosure requirements have actually caused the decline in the number of public companies, rather than merely coinciding with it in time?
- What is the starting point for measuring the decline in the number of public companies—1980, 2000, or another period?
- What empirical evidence supports the claim that "reducing disclosures will increase the number of public companies"?
- What is a "reasonable" level for the number of public companies? How will the SEC determine when disclosure reductions have gone far enough?
- What impact has the post-financial-crisis pursuit of yield, and investors' willingness to forgo transparency and liquidity in pursuit of higher returns in private markets, had on going public?
- Has the SEC considered the implications of rising market concentration and the declining number of public companies in the U.S. and globally?
- Given that many jurisdictions with relatively lighter disclosure regimes—such as the UK, the EU, and Hong Kong SAR—have also experienced similar declines in listings, how can disclosure requirements alone explain this trend?
Regarding technology
- How does the SEC account for issuers' use of AI when assessing the volume and materiality of disclosures?
- How does the SEC account for investors' use of AI when constructing the "disclosure overload" narrative?
- How will the SEC's newly established AI office contribute to the above analysis?
A call for public engagement
Following Chair Atkins' January 13statementdirecting the Division of Corporation Finance to conduct a comprehensive review of Regulation S-K (including reconsidering executive compensation disclosures), these questions have become even more important.
In his statement, Chair Atkins noted that since its adoption in 1982, Regulation S-K has been the SEC's core set of disclosure requirements outside of financial statements. He also noted that over more than four decades, this set has expanded significantly. Chair Atkins argued that Regulation S-K now elicits both material disclosures and a "vast amount of indisputably immaterial information," citing Justice Thurgood Marshall's warning inTSC Industries v. Northwayagainst drowning investors in a sea of immaterial details.
This concern deserves serious examination, but only on the basis of evidence and with a full understanding of how modern investors actually process information.
In histestimonyreleased before appearing before the House Financial Services Committee on February 11, and in nearly identicalstatementremarkstestimonyreleased before his appearance before the Senate Banking Committee the following day, Chair Atkins again advanced the "disclosure overload" narrative. This time, he claimed without citing a source that public companies spend $2.7 billion annually to file annual reports. remarks He suggested these funds could be used to create jobs and lower the cost of living for American families, but did not explain how reducing disclosure spending would achieve those outcomes.
Notably, his remarks made no mention of the fact that $2.7 billion represents only about 0.002% of the $124.3 trillion U.S. capital markets—a market he himself has described as the deepest and most liquid in the world. He also failed to recognize that the disclosure framework he criticizes, established under the Securities Acts of 1933 and 1934, helped build the transparency and investor confidence underpinning U.S. markets—now widely regarded as a global model.
Chair Atkins also displayed a prop at the House hearing: Entergy's 1,000-page Form 10-K. This visual was intended to highlight the burden of disclosure. However, Representative Bill Foster (D-Ill.) directly challenged this premise, noting that such documents can be analyzed by machines in minutes. He further pointed out that companies themselves are increasingly using AI to prepare disclosure documents. This was a sharp and effective challenge to the "disclosure overload" narrative, and Chair Atkins offered little substantive response.
Will private markets cannibalize the IPO market?
Ironically, at the same time the SEC is trying to stimulate IPO activity by reducing disclosures, policymakers are attempting to expand retail investor access to private markets through pooled investment vehicles. This raises a troubling question: Will private companies, with easier access to public investor capital through such retail channels, ultimately cannibalize the IPO market the SEC is trying to promote through its disclosure initiatives?
If private companies can access public capital while enjoying lower-quality accounting standards, limited disclosures, and opaque valuation practices, why would they choose to go public? Allowing private companies to access public capital without public market transparency is likely to reduce—not increase—the incentive for companies to seek public listings. The SEC should assess the extent to which these initiatives may have conflicting or offsetting effects.
If private companies can access public capital while enjoying lower-quality accounting standards, limited disclosures, and opaque valuation practices, why would they choose to go public? Allowing private companies to access public capital without public market transparency is likely to reduce—not increase—the incentive for companies to seek public listings. The SEC should assess the extent to which these initiatives may have conflicting or offsetting effects.